
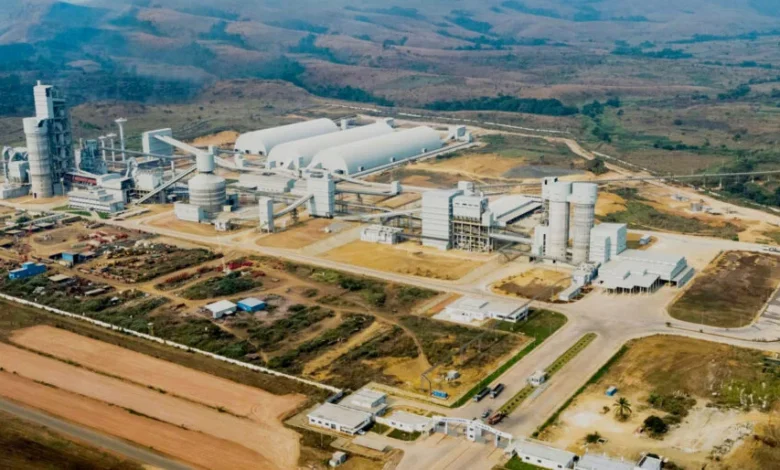
Cement Manufacturing Investment in Africa: 8 Promising Opportunities
Cement manufacturing investment in Africa now rewards owners of cheap clinker, not builders of the biggest kiln. Recent deals include Huaxin’s takeover of Lafarge Africa at a USD 1 billion equity valuation, a USD 110 million calcined clay plant in Ghana, and blended-finance grinding stations in Sierra Leone. Integrated plants cost approximately USD 87 to USD 170 per tonne of annual capacity, so the entry route shapes returns more than headline market growth does.
Technical Snapshot: Core Project Specifications
| Parameter | Detail |
| Market value (Africa) | USD 8.7 billion in 2025, forecast at USD 11.7 billion by 2029 (7.6% CAGR, value basis) |
| Investment volume | Integrated plants: approximately USD 87 to USD 170 per tonne of annual capacity.
Grinding plants: from about USD 15 million for 0.4 million tonnes per year |
| Top opportunity regions | West Africa’s clinker-importing coast (Ghana, Côte d’Ivoire, Sierra Leone), Kenya’s clinker-constrained market and Mozambique’s coastal grinding belt |
| Entry mode | Joint venture with a local or state partner, grinding first with phased clinker, brownfield acquisition, or greenfield integrated build |
| ROI horizon | Long cycle: integrated plants underwrite over 10 to 15 years. Grinding stations and blending lines skip the kiln, carry lower capex per tonne and shorten the payback window |
Investors who want to invest in the African cement industry need a map of where cement plant investment in Africa still earns a spread. This guide ranks eight routes by capital intensity, control and risk.
Introduction: Cement Manufacturing Investment in Africa
Cement manufacturing investment in Africa has moved beyond whether demand exists. The harder question is which link in the chain still earns a spread once new capacity comes online. Dangote Cement lifted its capacity to 55 million tonnes a year across the continent in early 2026 and targets 80 million by 2030. Nigeria’s competition regulator, meanwhile, cites 60 to 65 million tonnes of national capacity against consumption of 25 to 30 million in its cement price-manipulation findings. Capital keeps flowing anyway, because clinker, energy, and haulage costs still vary far more than demand does.
Investors who read Africa’s wider cement industry as one growth story miss where the margin sits. Cement is heavy, cheap per tonne, and expensive to move, so a plant earns a return only where it controls clinker, energy, or a delivery corridor. This guide ranks eight cement industry investment opportunities, from greenfield kilns to cross-border supply chains, with recent project costs, financing structures, and the failure points that sink returns.
Readers asking how to invest in cement manufacturing in Africa should start with entry mode, not country. The best cement investment opportunities in Africa reward partners who already have limestone, licences, or port access, and each route below carries a different capital bill and exposure. Anyone weighing equity, debt, or a plant of their own will find a direct comparison in the sections that follow.
Greenfield Plant Development in Underserved Markets
Within cement manufacturing investment in Africa, greenfield capacity offers the most control and the longest wait for revenue. New kilns make sense only where local clinker is scarce, and the market can absorb a full line within a few years. Research on high African cement prices finds that small national markets limit entry and explain most of the price premium, while falling cement prices in Africa tracked new entry: the average price dropped by about a third between 2011 and 2017 as plants arrived. For greenfield cement investment in Africa, the lesson is to arrive before the second producer does.
Recent projects show how far capex for greenfield cement plant investment in Africa moves with site and scope. PPC’s Western Cape plan, part of its capacity expansion in South Africa, sets the brownfield floor at approximately USD 107 per tonne. Remote first-of-kind plants set the ceiling: Cemtech’s Kenyan clinker plant sits near USD 170 per tonne, and a forthcoming Ugandan plant is near USD 150.
Table: Recent Integrated Plant Capex Benchmarks in Sub-Saharan Africa
| Project | Capacity | Reported capex | Approx. capex per tonne | Route |
| PPC Riebeeck, South Africa | 1.5 Mtpa cement | USD 159 million | USD 107 | Brownfield replacement |
| Moçambique Dugongo Cimentos, Nacala | 2.2 Mtpa cement | USD 192 million | USD 87* | Greenfield joint venture |
| Bamburi Matuga, Kenya | 1.6 Mtpa clinker | USD 250 million | USD 156* | New clinker line at an established operator |
*Calculated from reported capex and capacity.
A kiln sized for 2030 volumes needs those volumes on schedule, so investors should test the regional cement demand drivers against one catchment area rather than a national average. Small landlocked markets fail that test first.
Further Reading: Africa’s Cement Market: 7 Growth Drivers Powering Regional Demand
Joint Ventures with Local/National Producers
African cement joint ventures split the work by strength. The local or state partner brings land, limestone rights, licences, and political cover; the foreign partner brings capital, engineering contacts, and process know-how. Cement projects across South-East Africa show the model at scale: Moçambique Dugongo Cimentos pairs SPI Gestão with China’s West International Holding to build a 2.2 million-tonne integrated plant at Nacala.
Zambia offers the distressed-asset variant. In May 2026, ZCCM Investments Holdings and China’s Wonderful Group formed Ndola Lime as a 45:55 venture to restart the Ndola cement and lime plant, which closed in 2018 with 0.2 million tonnes of capacity. Wonderful commits USD 30 million, while ZCCM writes off USD 9.8 million of historic debt. The state contributes a clean balance sheet instead of cash, which lowers the foreign partner’s entry price.
Local alignment also protects against political risk. Huaxin agreed to buy Holcim’s 83.81% stake in Lafarge Africa, yet a minority shareholder launched a lawsuit over Lafarge Africa’s sale, and Nigeria’s Senate passed a resolution urging the federal government to stop it. Cement industry joint ventures in Africa avoid that friction when the partner comes from Africa’s top cement brands, because those names already hold the licences, dealer networks, and regulator relationships that a foreign company cannot buy.
Clinker Grinding Station Investment
Grinding stations put capital into the last step of cement making and leave the kiln to someone else. The model suits coastal markets that import clinker cheaply and want local cement fast. Mozambique runs ten grinding plants totalling 4.75 million tonnes per year against two integrated plants of 3.2 million tonnes, which shows how far the approach can go.
Sierra Leone’s MACCEM project sets the template. IFC’s backing for MACCEM’s local cement production covers a 657,000-tonne grinding plant in Freetown, the country’s first in four decades. The plant will meet up to 65% of national demand and integrate solar power.
Scale can shrink further when the clinker substitute sits on site. Tsingshan subsidiary DISCO is building a USD 15 million, 0.4 million tonne grinding plant at its Manhize complex in Zimbabwe, and the plant draws on captive granulated blast furnace slag. In every grinding case, the exposure is clinker: its price, its currency, and the policy around it all sit outside the plant gate.
Alternative Fuel and Waste-Heat Recovery Projects
Energy is the highest controllable cost in a cement plant, so retrofits that cut it attract lenders and pull cement manufacturing investment in Africa toward existing sites. Waste-heat recovery and alternative fuels address different levers: one turns exhaust heat into electricity, the other displaces coal, gas, or petcoke. The operating side of these retrofits belongs to cement manufacturing growth strategies; the investor question is whether each retrofit pays back at local power tariffs.
A peer-reviewed study of Ethiopian waste heat recovery shows how tariffs decide the outcome. The steam-cycle unit covers 18% of the plant’s electricity demand and pays back in 15 years at a 30% discount rate. A 20% capex overrun turns its net present value negative, while a 12% real discount rate lifts it to USD 18.4 million.
Table: Waste-Heat Recovery Economics for a 2.3 Million Tonne Plant in Ethiopia
| Technology | Output | Capital cost | LCOE | NPV at 30% discount rate |
| Steam Rankine cycle | 8.9 MW | USD 9.8 million | USD 0.04/kWh | +USD 0.35 million |
| Organic Rankine cycle | 10.7 MW | USD 14.9 million | USD 0.06/kWh | -USD 3.2 million |
| Kalina cycle | 11.5 MW | USD 17.3 million | USD 0.06/kWh | -USD 4.7 million |
Ethiopia’s cheap hydropower caps the return. Grids that lean on gas or diesel value recovered power higher, so the same unit pays back faster there. Alternative fuels move more slowly: at Dangote’s Ibese alternative fuel co-processing project, use rose from 3,488 tonnes in 2021 to 96,761 tonnes by October 2025, a 6.6% thermal substitution rate, and the operator names sourcing cost, community, and regulatory issues as the hurdles. Bamburi’s Kwale clinker plant is designed to use coconut husks, cashew shells, and municipal waste.
Further Reading: Cement Manufacturing in Africa: 8 Powerful Strategies Driving Market Growth
Blended Cement and SCM Production Facilities
Blended cement cuts the most expensive input in the bag. Clinker carries the fuel, the kiln capex, and, in many African markets, an import bill. Substituting limestone, fly ash, slag, or calcined clay for part of it turns a cost problem into a product line. LC3, the limestone-calcined clay blend, leans on African calcined clay projects such as CBI Ghana’s, whose calciner should substitute 30 to 40% of clinker and cut CO₂ per tonne by up to 40% compared with ordinary Portland cement.
CBI Ghana shows what’s now possible at scale. Its USD 110 million plant at the Tema Free Zones Enclave, the world’s largest calcined clay plant, opened on 5 March 2026 with capacity for more than 400,000 tonnes a year. The output targets Ghana’s clinker import bill, which nears USD 500 million annually, and calcined clay at an industrial scale lets CBI swap a large share of that imported clinker for local clay.
Standards gate the market. Supacem’s LC3 plant launch followed the Ghana Standards Authority’s adoption of the GS PAS 5:2024 specification, so investors should treat standards approval as a funding condition, not an afterthought.
Logistics and Distribution Infrastructure
Cement travels badly. A tonne loses margin on every road kilometre, so terminals, depots, and fleets often earn more than the factory behind them. Even Africa’s largest producer struggles with the last leg: Dangote now plans to acquire a vessel for regional exports after failing to find a ship for a 1,000-tonne consignment from Nigeria to Ghana, and road exports face extra taxes when crossing Benin and Togo.
Volumes justify the logistics build. Dangote’s cement and clinker exports rose 18.6% to 1.4 million tonnes in 2025, driven by 34 clinker shipments to Ghana and Cameroon, and Dangote’s Africa capacity push targets 80 million tonnes by 2030. Coastal receiving terminals and inland depots that shorten the last leg capture value even without owning a kiln.
Kenya’s cement market outlook points to the other side of the trade: supply constraints and clinker bottlenecks keep delivered prices volatile, which favours anyone who can hold stock and deliver on schedule. The investable assets are bulk terminals, rail sidings, silos and truck fleets, and contracted throughput makes them simpler to underwrite than a kiln.
Brownfield Capacity Upgrades and Modernisation
Brownfield capital buys capacity more cheaply than a new kiln, making it the quiet centre of cement manufacturing investment in Africa. Holcim’s Nigerian business sale valued Lafarge Africa at USD 1 billion in equity on a 100% basis for 10.5 million tonnes of installed capacity across four plants, or approximately USD 95 per tonne. That compares with USD 107 to USD 170 per tonne for the newer integrated projects above, although the equity figure excludes debt.
Modernisation follows the same logic. PPC’s USD 160 million, 1.5 million tonne Western Cape plant replaces and increases capacity at two older sites while both keep running through construction. Huaxin’s Mozambican subsidiary tripled its Nacala plant to 1.2 million tonnes per year for USD 110 million and finished the work on 28 July 2026.
Policy can make an upgrade pay. Kenya’s clinker import levy of 17.5% cut clinker imports from 148,000 tonnes in 2023 to 10,300 tonnes in 2024, and the trade ministry has since dropped its plan to repeal it after President Ruto rejected the idea. Bamburi answered with its Sh32bn Kwale clinker plant, which lifts its clinker capacity from 1 million to 2.6 million tonnes. Kenya’s leading cement companies already include Bamburi, so the new line deepens an established position rather than opening a new front.
Cross-Border Regional Supply Ventures
Cross-border ventures monetise surplus capacity in one country by selling it into a neighbour. The model works when one market overbuilds, and the next underbuilds. Dangote’s Nigerian cement and clinker exports rose 71.6% in the first quarter of 2026, with ten clinker shipments sailing to neighbouring markets. Tanzania produced 10.3 million tonnes against domestic demand of 8.5 million and shipped the difference to Malawi, Zambia, the DRC, Rwanda and Burundi, even as cement prices in Tanzania climbed toward USD 10 a bag in places.
Financing follows the trade. Dangote commissioned a 3 million tonne grinding plant in Côte d’Ivoire, and EBID’s approved West Africa investments include a USD 25 million facility for Société de Ciment de Côte d’Ivoire to import 400,000 tonnes of clinker.
Paper tariffs are not the constraint. EAC leaders set 30 June 2026 to remove non-tariff barriers, but the EAC trade-barrier deadline lapsed with 28 barriers outstanding at the May review and intra-regional trade stagnant at around 15% of total trade. Regional supply ventures therefore need a plant on each side of a border, or long-term off-take contracts, rather than a single export hub.
Financing Cement Plants in Africa: Structures, Underwriting and Investment Risks
Capital structure decides which route to cement manufacturing investment in Africa closes. This block covers how lenders stack cement financings, how to size demand in tonnes and which risks recur across deals.
1. Financing Structures for Cement Plants in Africa
Financing cement plants in Africa usually layers development-finance senior debt, concessional blended-finance money, commercial bank tranches, and sponsor equity. In the two smallest packages below, a concessional window supplies about half the debt, which lets a small grinder reach bankability. Cement sector financing in Africa also reaches beyond plant debt, because working-capital lines for clinker imports sit in the same stack.
Table: Recent Development-Finance Cement Packages in Africa
| Borrower | Package | Structure | Use |
| CIMAF (OIP Group): Senegal, Mali, Ghana | €161.25 million | IFC €92.5 million own account, Proparco €33.75 million parallel loan, EAIF €35 million B loan | Greenfield integrated plant at Pout; grinding expansions in Mali and Ghana |
| MACCEM, Sierra Leone | USD 24 million | USD 12 million IFC loan plus USD 12 million IDA20 blended-finance loan | 657,000-tonne grinding plant |
| Fouta Cement, Liberia | USD 21.1 million | USD 5.4 million IFC, USD 10.8 million IDA private sector window, up to USD 5 million commercial | 0.35 million tonne grinding plant |
| Société de Ciment de Côte d’Ivoire | USD 25 million | EBID facility | Clinker imports |
The IFC-arranged CIMAF financing shows the same layering at an integrated scale, while Fouta Cement’s plant financing shows a commercial bank joining alongside concessional money.
2. Underwriting Market Size in Tonnes, Not Headline Values
Published continental market values disagree by a factor of four. Africa’s cement forecast to 2029 sits beside a much larger figure for Africa’s cement investment opportunities, and the East Africa cement outlook sits far below both. Scope definitions explain the spread, so investors should treat each figure as a definition, not a forecast.
Table: Published Cement Market-Size Estimates for Africa
| Scope | Base value | Growth |
| Africa (market-research databook) | USD 8.7 billion (2025) | 7.6% CAGR, 2025 to 2029 |
| Africa (investor portal) | USD 35 billion | 4.7% CAGR, USD 42 billion forecast |
| East Africa (market-research report) | USD 2.7 billion (2025) | USD 3.0 billion by 2034 |
Tonnes of demand inside a haul radius give a firmer base, and the gap between capacity and consumption shows how much of that demand is already claimed.
Table: Installed Capacity Against Domestic Demand in Three Markets
| Market | Capacity | Domestic demand | Capacity-to-demand ratio |
| Nigeria | 60 to 65 Mtpa | 25 to 30 Mtpa | 2.0x to 2.6x |
| Tanzania | 13.6 Mtpa | 8.5 Mtpa | 1.6x |
| Zimbabwe (integrated, after Chegutu) | 3.9 Mtpa | 1.8 Mt (2025) | 2.2x |
3. Cement Manufacturing Investment Risks in Africa
Cement manufacturing investment risks in Africa cluster into four groups, and each one has a named case from the past year.
- Energy and currency. Industry participants told Nigeria’s regulator that energy costs, naira depreciation on imported machinery and spares, and transport drive prices. A plant that sells in local currency and buys spares in dollars carries a structural mismatch. Match debt currency to revenue, or export to earn dollars.
- Regulatory intervention. Nigeria’s Federal Competition and Consumer Protection Commission (FCCPC) found preliminary evidence of possible price manipulation in a market where three producers hold 90% of output, although the commission stresses that its findings are not final. Tanzania gave producers eight days to cut prices after bags reportedly neared USD 10 in places. Kenya’s trade ministry dropped its plan to repeal the clinker levy, so investors should assume that protection stays.
- Overcapacity. The ratios above matter because new entrants compress margins: the 2011 to 2017 price fall coincided with new plants. Zimbabwe’s Chegutu plant, due to start in September 2026, raises overcapacity concerns for a landlocked market whose demand sits far below its installed capacity.
- Counterparty and deal risk. A Zimbabwean court found in February 2026 that Livetouch Investments breached its contract by failing to pay a local supplier. Deal risk sits beside it: the Lafarge Africa litigation and the missed EAC deadline show that signed agreements still meet local resistance.
Conclusion: Back Clinker Independence, Not Headline Tonnes
The best cement investment opportunities in Africa sit in three routes, and the evidence favours them. The Brownfield acquisition buys capacity at about USD 95 per tonne, while new kilns cost USD 107 to USD 170. Grinding stations paired with local clinker substitutes, as in Tema and Freetown, remove the import exposure that drives price spikes. Joint ventures with a state or national partner, as in Nacala and Ndola, buy the licences and legitimacy that a cheque cannot. Together, these routes give the best ratio of control to capital across the deals reviewed here.
Avoid new integrated capacity in landlocked or already oversupplied markets, and skip waste-heat recovery where power costs USD 0.04 per kWh. Anyone deciding how to invest in cement manufacturing in Africa should treat the sector as a clinker-and-haulage bet: build a tonnes-based demand model first, secure clinker or limestone before ordering equipment, and price regulatory risk in Nigeria, Kenya, and Tanzania into the discount rate. Cement manufacturing investment in Africa will continue to add capacity. Returns will accrue to the owners of the cheapest clinker and the shortest haul.
Track the Capital Behind Africa’s Cement Build-Out
Construction Frontier’s Cement & Concrete coverage follows the deals, financing packages and regulatory rulings that decide where cement manufacturing investment in Africa lands. Follow it for plant-level project costs, joint venture structures, clinker economics and competition-authority decisions that move returns. Investors, lenders and project professionals use these briefings to test a thesis against live market evidence before they commit capital.